
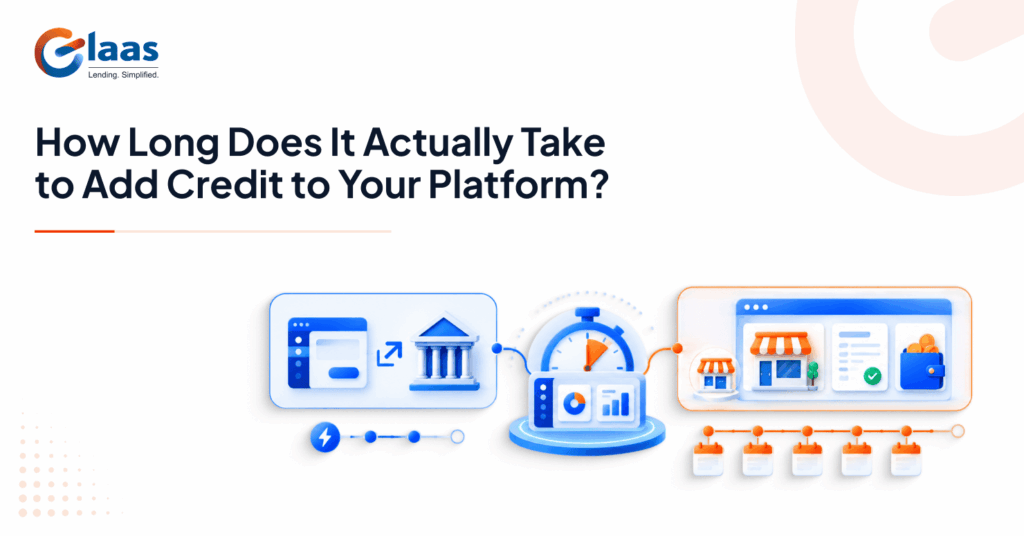
If you’re considering embedded credit, implementation time is usually one of the first practical questions: how quickly could this actually go live?
A co-branded no-code journey can go live in under 2 days. A fully native integration, where the credit experience is built inside your product, typically completes under 2 weeks.
The gap between those two paths, in effort and in what the merchant actually experiences, is wide enough to matter.
Key Takeaways
- A no-code co-branded journey can go live in under 2 days. A fully native integration, built inside your product, typically completes in under 2 weeks.
- Data preparation, internal approvals, and experience design decisions can extend the overall timeline before and during the build.
- Platform transaction data can add underwriting signals that a bureau score alone may not capture.
- What goes live first is a working version. Once live, the platform has real usage data to refine the credit offer over time.
- After a merchant is approved, disbursement happens within hours.
What are the Different Integration Options?
| Integration path | Platform engineering | Typical GLAAS timeline | Experience |
| Co-branded no-code | Minimal | Under 2 days. | Hosted/co-branded journey. |
| Native API | Required | Under 2 weeks. | Credit journey inside the platform. |
| Custom/hybrid | Depends on scope | Depends on requirements. | Mix of native and hosted components. |
Embedded credit is not a single thing. At one end is a co-branded no-code journey, hosted and managed by the lending partner but visually consistent with your platform. Your team configures when and how the offer appears to merchants; the lender handles the lending process behind it. This can go live in under 2 days, with no API work on your side.
At the other end is a native integration, where the credit offer, application, status updates, and disbursement notifications are all built inside your product using the lender’s API. The merchant can complete the credit journey without leaving your platform. A fully native integration typically completes in under 2 weeks.
In between are various levels of customisation, from co-branded journeys with heavier UI work to partial API integrations that handle some parts natively and some through the hosted journey. Where you land depends on how central you want the credit experience to be inside your platform and how much engineering capacity you can put towards it.
Where Does Time Go in a Native Integration?
For teams planning a native build, a few things can extend the timeline beyond the engineering itself.
Data Readiness
The lending partner needs to assess your merchants to underwrite them. Platform transaction data, payment history, and order patterns can add underwriting signals that a bureau score alone may not capture, such as transaction frequency, order regularity, and payment behaviour over time. For that data to be useful, it needs to be in a form the lender can work with. If it sits across multiple tables, has missing timestamps, or was structured for an internal reporting tool rather than external sharing, preparation can add real time before the build begins.
Internal Approvals
A project that touches merchant data, the payment experience, and how your platform communicates with users may need sign-off from more than one team. Product, legal, and sometimes finance all have a view. Getting that alignment in place can extend the timeline, not because teams disagree, but because the question is often being formally put for the first time.
Experience Design
When and how you show the credit offer to a merchant matters. An offer shown at the wrong point in the journey, or framed poorly, can affect how merchants engage with it. Getting the framing right takes thinking time that the engineering estimate doesn’t always include.
What Happens After You Go Live?
Launch is not the finish line, though it tends to feel like one. What ships first is a working credit journey. Once live, the platform has real data to work with:
- Which merchant segments engage with the offer.
- Where in the purchase journey the offer lands best.
- What repayment behaviour looks like.
- Where merchants drop out of the application.
That data makes it possible to refine offer placement, merchant targeting, messaging, and the application journey itself. Disbursement, once a merchant is approved, happens within hours.
What is the Platform Actually Building?
Worth being clear on before scoping: the platform is not building a lending product. It’s building the merchant experience that sits in front of a lending product someone else runs.
In a native integration, your engineering team connects to a partner API, your product team designs the screens, and you decide when and how to surface the credit offer. In the no-code path, the hosted journey handles the screens; your team configures the offer entry point and the branding. In both cases, the lender handles underwriting decisions, capital deployment, and collections.
That’s a meaningful distinction when scoping the project, because the lending-specific logic is not yours to build or maintain.
How GLAAS Works
Platforms that want to offer their merchants working capital can work with GLAAS. The co-branded no-code journey goes live in under 2 days. A fully native API integration, where the credit experience is built inside your product, typically completes in under 2 weeks. Merchants receive disbursement within hours of approval.
GLAAS operates through Gromor Finance, its RBI-licensed NBFC. The platform controls how credit is surfaced to its merchants; GLAAS handles underwriting, disbursement, and collections. Since launch, ₹1,500 Cr+ has been disbursed across 110,000+ loans to 13,000+ MSMEs, with a 70% repeat loan rate.
If your platform is at the point of asking how long this takes, the next step is a short conversation with the GLAAS team. Get in touch: contact@glaas.co or 98336 69351.
Frequently Asked Questions
1. Can a platform go live with embedded credit in under a week?
Yes, for a co-branded no-code journey. The lending partner provides the hosted journey; your team configures the offer and connects the entry point in your interface. This path is designed for platforms that want to launch without committing engineering resources to a full native build. Under 2 days is the realistic timeline for this option.
2. Who builds the merchant-facing screens in a native integration?
Your product team builds them against the lender’s API. The lender provides documentation and a sandbox for testing. The design decisions, when the offer appears, how it’s framed, and what the status updates say, are yours to make and iterate on after launch. For the co-branded no-code path, the hosted journey provides the screens; your team configures the offer rather than building the interface.
3. What merchant data does the lender typically need before going live?
Transaction history is an important input: how much a merchant transacts on the platform, how regularly, and whether their payment behaviour has been consistent. Cleaner, well-structured data is easier to use in underwriting.
4. What is GLAAS and who does it work with?
GLAAS provides embedded credit infrastructure that enables B2B platforms (marketplaces, distribution networks, supply-chain anchors) to offer their merchants working capital without holding the loans on their own books. GLAAS operates through Gromor Finance, an RBI-licensed NBFC, which handles the regulated side of the credit business. More than 13,000 MSMEs have been funded since launch, across multiple sectors.
5. Does a platform need a lending licence for the integration?
The platform does not need to become an NBFC to offer credit through this model. The lending licence sits with Gromor Finance. The platform’s exact responsibilities depend on the programme and integration structure.